Blog - SGW Payment

Network Tokens Are Now Expected on Stored Cards in Europe: What It Means for Subscription Renewals

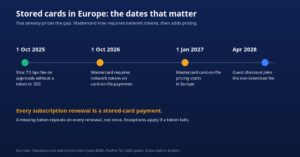
Since 1 October 2026, Mastercard requires Credential-On-File transactions in Europe to be processed with network tokens, with exceptions. Visa already charges 7.5 basis points on domestic and intraregional approvals without a token or 3DS. Mastercard adds card-on-file pricing in Europe from January 2027. Subscription renewals are stored-card payments, so they carry the exposure. Audit your token coverage this quarter.
Read More »

Australia’s Card Surcharge Ban Is Live: What It Means for Subscription Billing Margins

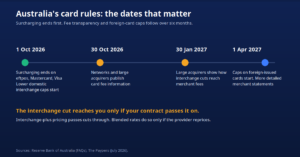
Since 1 October 2026, card networks no longer permit surcharging on eftpos, Mastercard, and Visa credit, debit, and prepaid cards in Australia, including internationally issued cards. Lower interchange caps apply to domestic card transactions from the same date. Caps on foreign-issued cards start on 1 April 2027. Subscription businesses lose a way to pass card costs to customers. Whether they gain from lower interchange depends on their pricing contract.

Read More »

Mastercard’s TLID Mandate: What Subscription Businesses Must Change Before Renewals Break

From October 2026, Mastercard expects merchants to send a Transaction Link Identifier (TLID) on subscription renewals and other merchant-initiated payments, with non-compliance fees starting in January 2027. The identifier must persist across every system that touches a payment: billing, gateway, orchestration layer, and processors. A single dropped hop breaks the link. Businesses that route renewals across several providers or several countries have the most places where the identifier can get lost.

Read More »

What the Walmart-Led Objection to the $200 Billion Visa-Mastercard Settlement Means for Subscription Billing

On September 15, 2026, Walmart and roughly 900 other merchants and trade associations filed objections asking a federal court to reject final approval of the revised $200 billion Visa/Mastercard interchange settlement, or to let them opt out. The settlement would cut credit interchange rates by 0.1 percentage points for five years and cap standard consumer card rates at 1.25% for eight years. For subscription and recurring-billing businesses, interchange is one cost line among several, and approval rate and transaction routing are levers a business can act on this quarter, independent of how the litigation resolves.

Read More »

What Two FTC Payment Processor Settlements Mean for Subscription Billing’s Chargeback Risk

On September 4 and September 9, 2026, the FTC settled with payment processor Nuvei ($4.85 million) and ISO Humboldt Merchant Services ($12 million) over inadequate screening of high-risk and fraudulent merchants. Both orders require processors to actively monitor merchant chargeback rates and cut off anyone crossing risk thresholds, the same kind of thresholds Visa already enforces through its Acquirer Monitoring Program (VAMP). Subscription and recurring-billing merchants run structurally closer to those thresholds than one-off retail, because a disputed failed renewal counts the same as fraud in the ratio.

Read More »

A Payments Processor Just Bought a Bank: What Vertical Integration Fixes for Subscription Billing, and What It Doesn’t

On September 2, 2026, TabaPay closed $155 million led by FTV Capital and announced plans to buy Transact Bank, N.A., an OCC-chartered, FDIC-insured bank in Denver. It would become TabaBank, N.A., with closing expected in Q4 2026 subject to regulatory approval. Owning a charter removes a processor’s dependence on sponsor banks, opens direct access to Federal Reserve rails, and replaces state-by-state licensing with one federal framework. It is a rational move for the processor. For a subscription business, that vertical integration deepens one provider path. It does not create a second one, and a US charter does nothing for the approval odds of a renewal on a card issued in another country.

Read More »

What the Fed’s FedNow Cross-Border Proposal Fixes, and Doesn’t, for Subscription Billing

On April 10, 2026, the Federal Reserve proposed amending Regulation J to let FedNow participants route transfers through intermediary banks, including non-U.S. correspondent banks, extending real-time settlement to the U.S. leg of cross-border payments for the first time. On August 10, Stripe, Visa, Wise and a coalition of banking and fintech trade groups formally backed the proposal, though the Fed has not set a timeline for a final rule. The change only fixes settlement speed on the domestic leg. It does nothing for authorization, where a cross-border card transaction still clears at lower approval odds than one processed locally, which is the problem orchestration and local-market infrastructure actually address.

Read More »

What Mastercard’s August 2026 Outage Means for Subscription Renewal Resilience

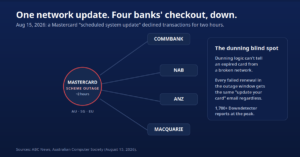
On August 15, 2026, a scheduled Mastercard system update took transactions offline across Australia, Singapore and parts of Europe for close to two hours, with Commonwealth Bank, NAB, ANZ and Macquarie all confirming the fault sat with Mastercard. For subscription billers, a scheme-level outage isn’t a retail glitch, it’s a wave of renewal failures dunning systems can’t distinguish from ordinary card declines unless routing already spans more than one provider.

Read More »

UK Card Fee Transparency Rules: What the PSR’s Visa and Mastercard Directions Mean for Subscription Billing

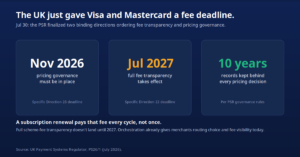
On July 30, 2026, the UK’s Payment Systems Regulator finalized two binding directions ordering Visa and Mastercard to disclose how they set scheme fees charged to acquirers, with compliance deadlines running from November 2026 through July 2027. For subscription businesses, undocumented scheme fees repeat on every renewal, compounding against MRR long before UK acquirers get full transparency.

Read More »

The Credit Card Competition Act Returns to Congress: What It Would Mean for Subscription Billing Margins

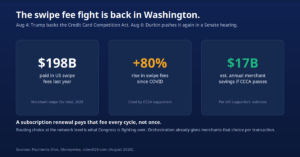
On August 4, 2026, President Trump publicly endorsed the Credit Card Competition Act, calling swipe fees a “ripoff.” The bill would require large banks to give merchants a routing choice beyond Visa and Mastercard on every card transaction. US merchants paid $198 billion in swipe fees last year, up more than 80% since COVID. Routing choice at the network level is the mechanism at stake in Washington, and payment orchestration already gives merchants that choice at the transaction level today.

Read More »